
 Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
Introduction
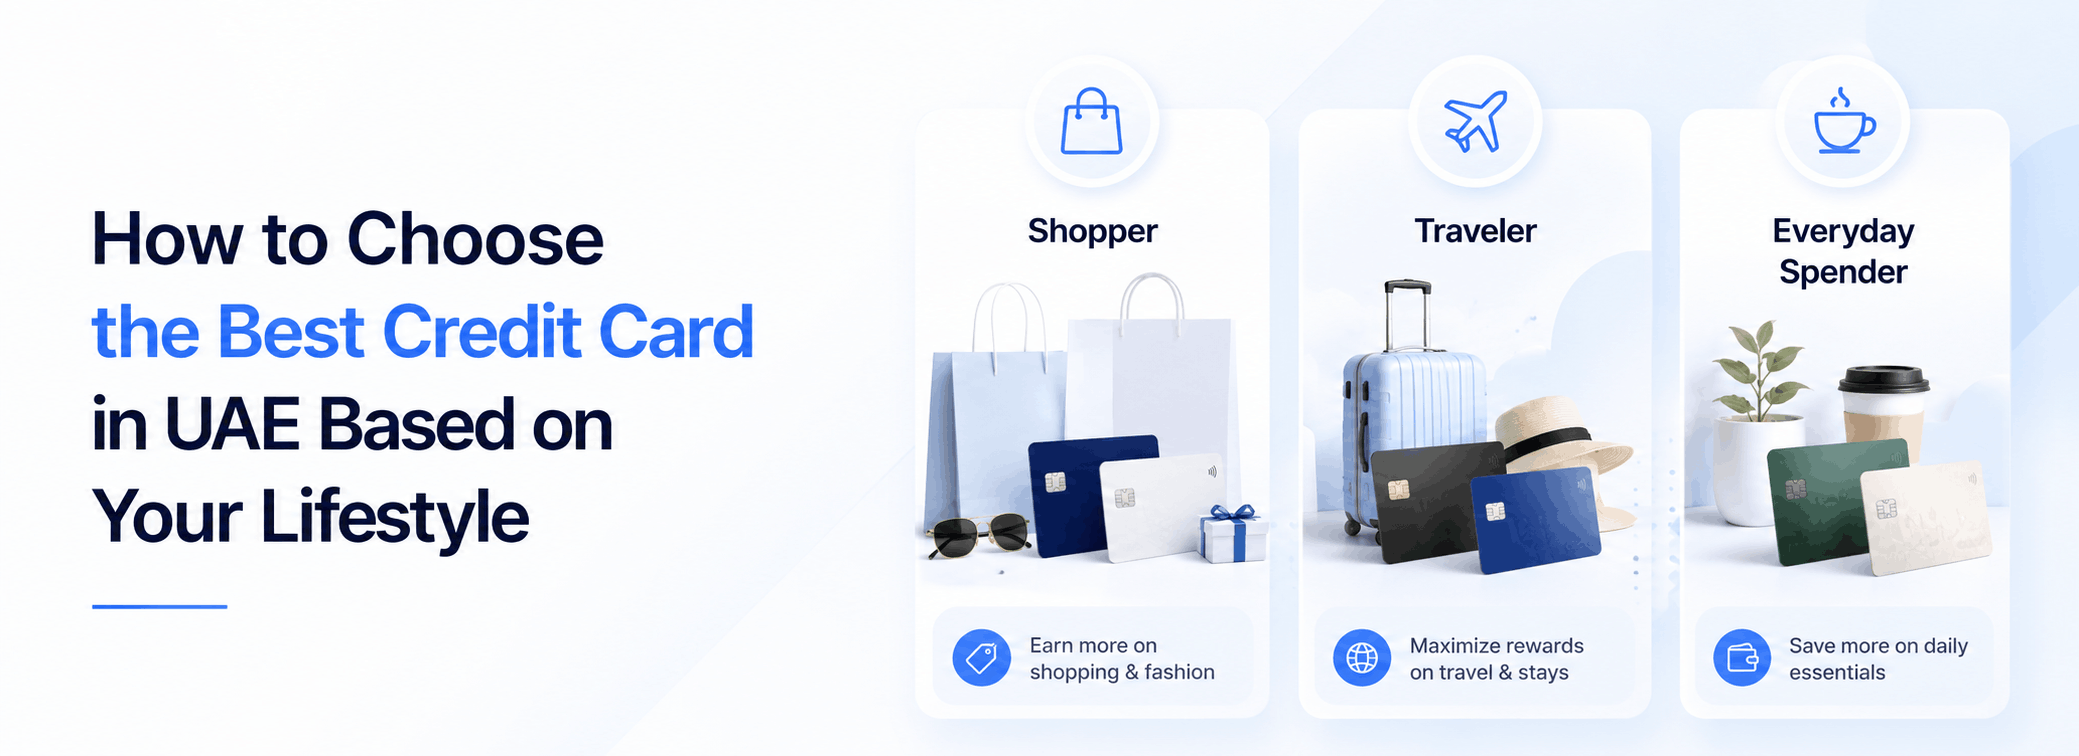
The UAE is packed with credit card offers promising cashback, airline miles, airport lounge access, shopping points, and more. With so many options, it’s tempting to pick the flashiest brochure. But the smarter strategy is simple: choose a credit card that matches your lifestyle. When your card’s perks align with your spending habits, you maximize rewards; when they don’t, fees and unused benefits add up.
This guide breaks the process into four actionable steps: identify your spending style, understand UAE credit card types, compare cards easily, and apply smartly for approval. Follow these steps to find the best UAE credit card for you in 2025.
Step 1: Match Your Credit Card to Your Lifestyle
Your spending habits are your “money map.” Identify the profile that fits you best:
1. The Frequent Flyer
- If you travel often for work or leisure, a travel credit card is ideal. Look for:
- Air miles on everyday purchases
- Airport lounge access
- Travel insurance
- Seat upgrades
- Regular use can offset airfare costs and make trips smoother.
2. The Everyday Spender
If most of your budget goes to groceries, fuel, and dining, a cashback card works best. You’ll earn money back automatically, helping to reduce everyday expenses without extra effort.
3. The Cost-Conscious User
For those who want simplicity, a no-fee or low-interest credit card keeps costs predictable. You won’t chase rewards; you value transparency and straightforward statements.
4. The Points Collector
If you enjoy turning spending into rewards, a points-and-perks card converts every dirham into vouchers, gift cards, electronics, or experiences. Flexibility matters more than immediate cash.
Tip: Review last month’s spending to identify your top categories. Your card choice should match where your money goes.
Step 2: Understand UAE Credit Card Types
Banks in the UAE design cards for specific goals. Knowing these types helps you narrow your choices:
1. Money-Back (Cashback) Cards
Offer a fixed percentage return on everyday spending. Perfect for families and commuters who want automatic savings without tracking partner networks.
2. Travel Mile Cards
Convert purchases into airline miles for flights, upgrades, or partner travel perks. Ideal for travelers flying a few times per year.
3. Points-and-Perks Cards
Earn points redeemable for shopping, dining, experiences, or gadgets. Best for users who like variety and seasonal promotions.
4. Balance Transfer Cards
Transfer existing card debt to a new card with low or zero interest for a limited time. Useful for paying off debt efficiently within the promotional period.
5. Sharia-Compliant (Islamic) Cards
Operate without conventional interest, using permissible fees or profit models, while still providing rewards. Perfect for users seeking Islamic finance-compliant options.
Start by selecting the card family that matches your spending profile, then compare individual cards within that category.
Step 3: Compare UAE Credit Cards Easily
When two cards seem similar, ask these five questions:
Where do the best rewards apply?
Focus on categories where you spend the most—fuel, groceries, or dining.
Are there limits or thresholds?
Some cards cap rewards or require minimum spending. Make sure they align with your habits.
What are the total costs?
Consider annual fees, foreign transaction charges, cash withdrawals, and late fees.
How simple is redemption?
Cashback is straightforward; points or miles require checking redemption options and limitations.
Which perks will you actually use?
Lounge access, dining discounts, extended warranties, or travel insurance only matter if you can use them.
A card that answers these questions well for your lifestyle is likely the right pick.
Step 4: Apply Smartly in the UAE
Following these steps can improve your approval odds:
Check eligibility: Verify minimum salary, age, and residency requirements.
Prepare documents: Emirates ID, passport, bank statements, and salary proof.
Submit a focused application: Apply for one card at a time to avoid extra checks.
Activate and control: Enable app alerts, set limits, and track spending in real-time.
Using a trusted comparison portal can help filter options, but your final choice should always match your spending profile.
Make Your Credit Card Work Harder
Pay on time: Automate at least the minimum payment; late fees can outweigh rewards.
Align bills with your card: Use cards with high rebates for utilities or telecom bills.
Mind overseas transactions: Choose cards with favorable FX rates if you travel frequently.
Track promotions: Set reminders for welcome bonuses or limited-time offers.
Review annually: Lifestyle changes may require a new card for maximum value.
Conclusion
There’s no universal “best” credit card in the UAE. The best choice depends on your lifestyle:
Frequent flyers: Travel cards with miles and lounge access
Families & daily spenders: Cashback cards
Minimalists: Fee-free or low-interest cards
Reward enthusiasts: Points-and-perks cards
By mapping your spending, selecting the right card family, comparing options, and applying smartly, your credit card becomes more than plastic—it’s a tool that saves money, enhances experiences, and rewards your everyday spending.
Ready to put this into action?
Explore credit card options that may suit your profile, or estimate the numbers first with our UAE calculators. Eligibility applies.
This article is for general information only and does not constitute financial advice. FinShark is a marketing and information platform, not a bank, lender or financial adviser. Products are offered by third-party issuers and are subject to issuer eligibility criteria, fees, documentation and terms. T&Cs apply.