
 Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
Credit card decisions
Understand card types, annual fees, rewards, cashback, minimum payments, interest/profit charges and eligibility criteria.
Clear, calm explainers on credit cards, loans, banking and money in the UAE. No jargon, no pressure — just information to help you make the first move with more confidence.
New to the UAE? Credit card eligibility depends on more than salary. Employment, existing debt, credit history and documentation can all influence the outcome.
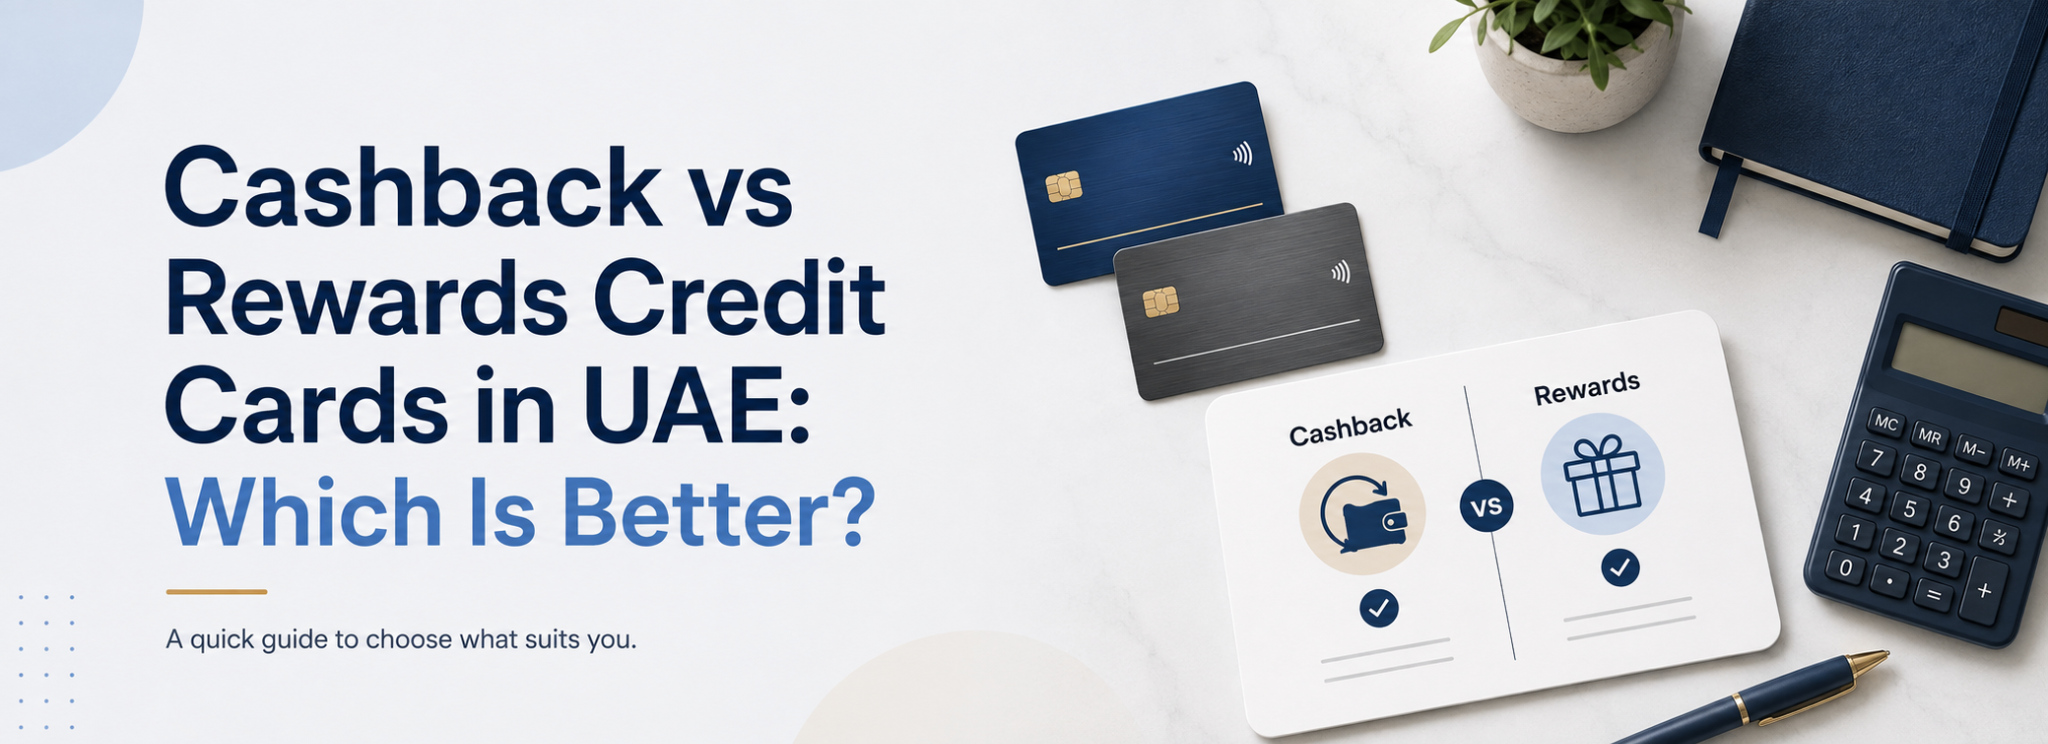
Cashback and rewards cards can both offer value, but the better choice depends on how you spend, how easily you redeem and what the card costs.
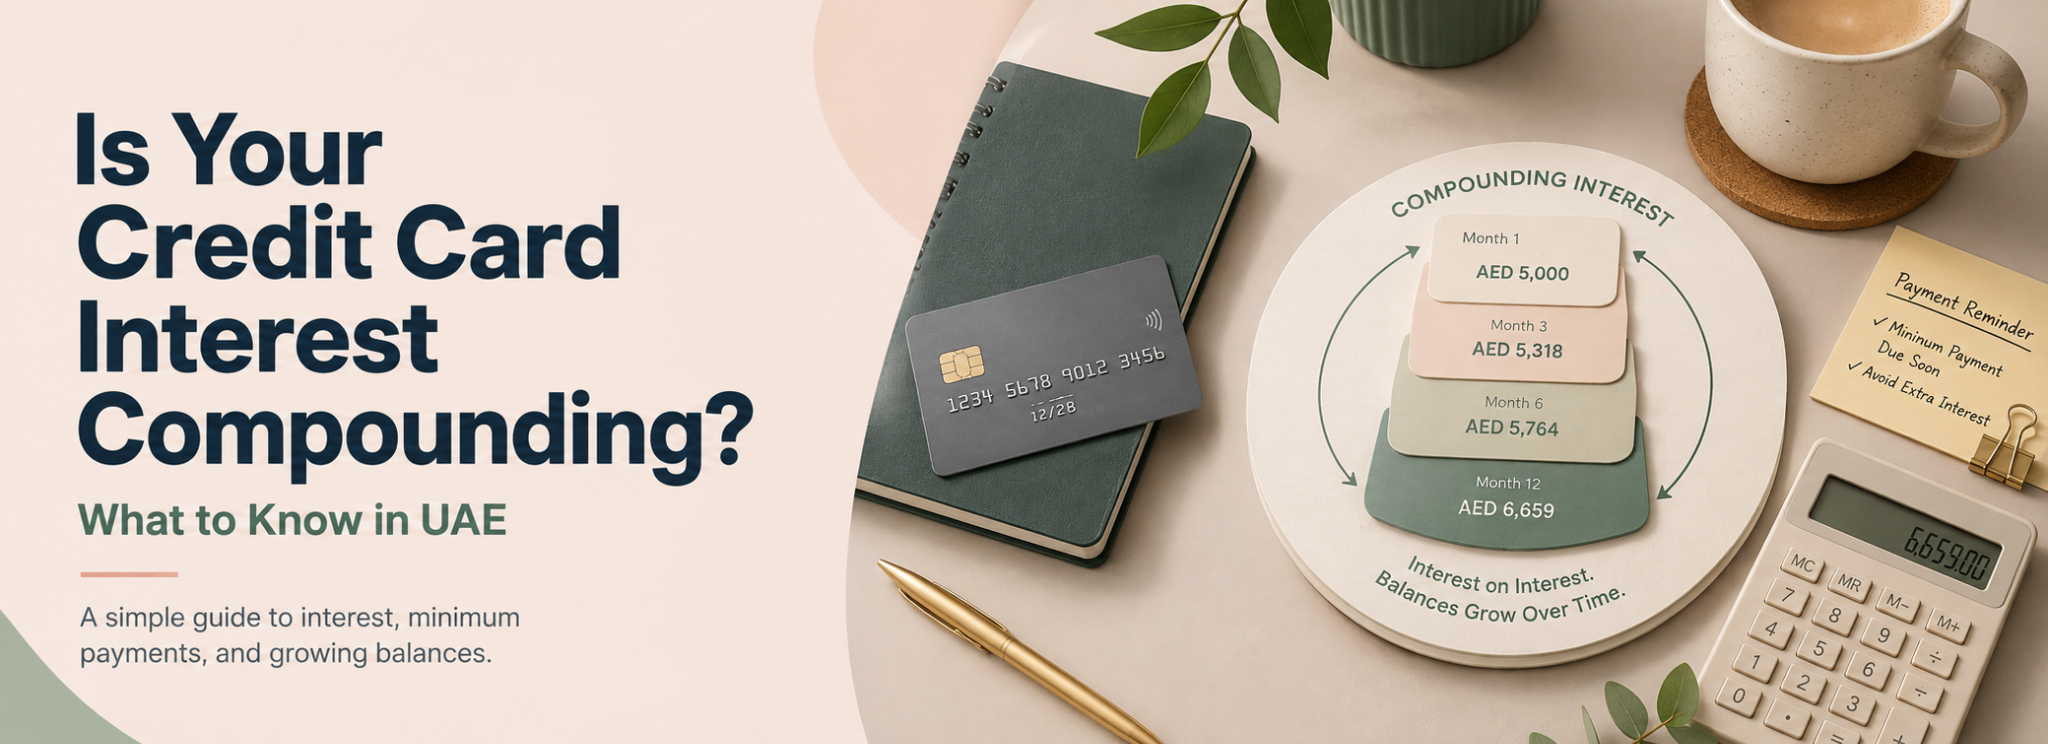
Carrying a credit card balance can make purchases more expensive over time. Understand how finance charges work and why repayment speed matters.
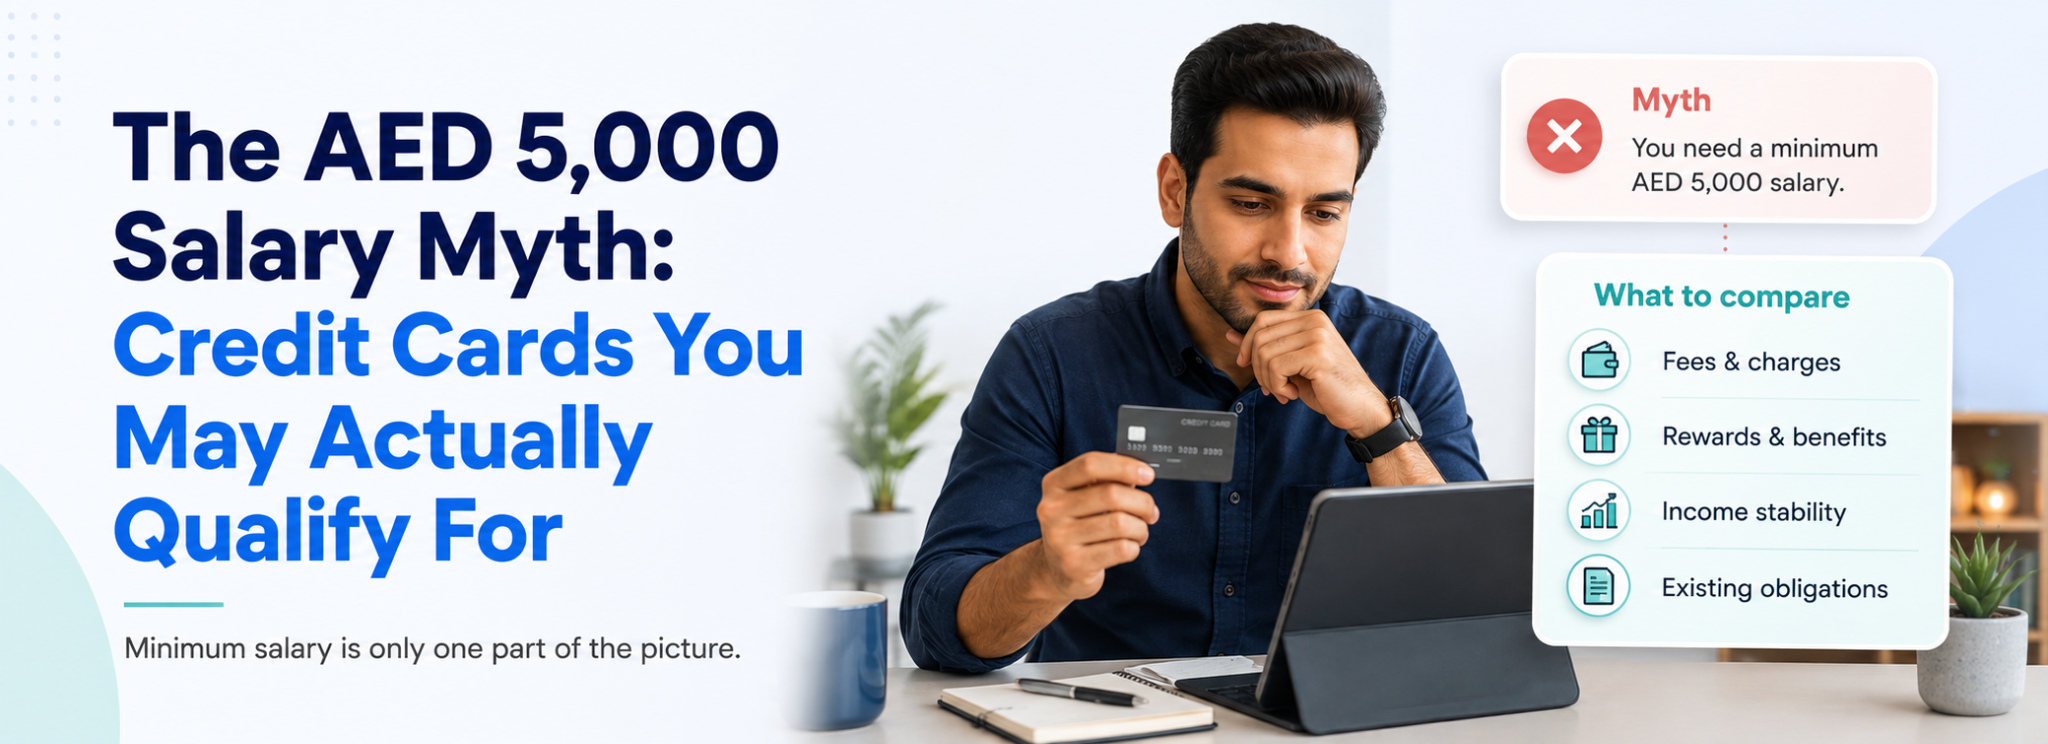
Earning AED 5,000 does not automatically guarantee or rule out a credit card. Salary is only one part of UAE credit card eligibility.
Comparing UAE credit cards is easier when you focus on salary fit, everyday spending, fees and benefits you will actually use.
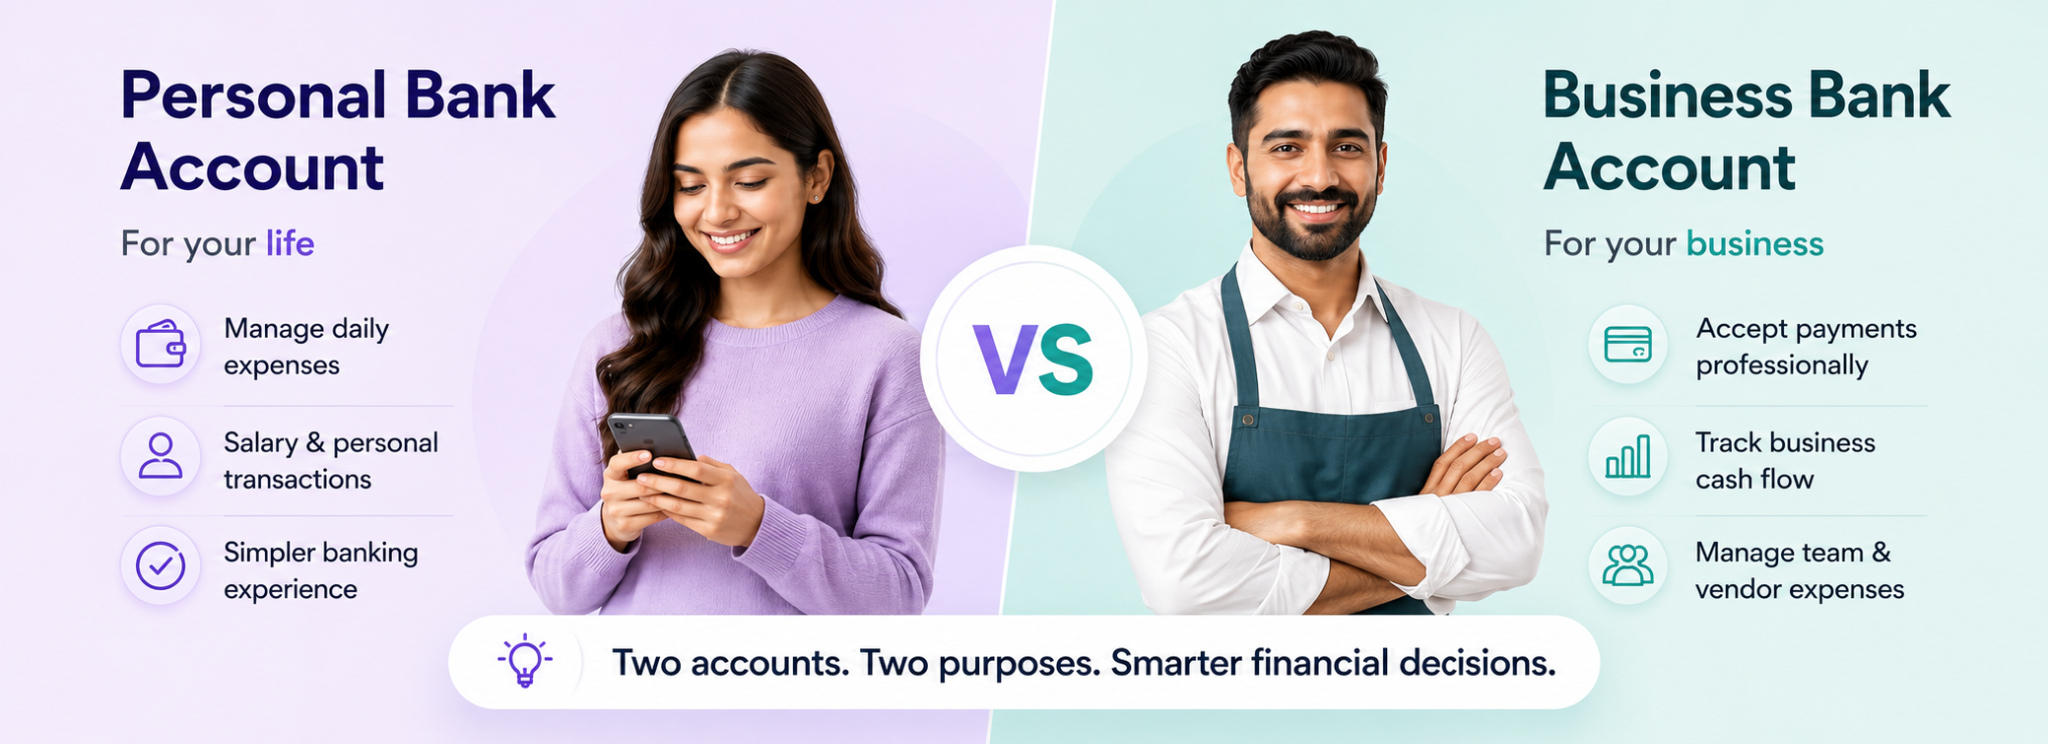
Personal and business bank accounts serve different purposes. Understand how they differ in usage, documentation and day-to-day money management.
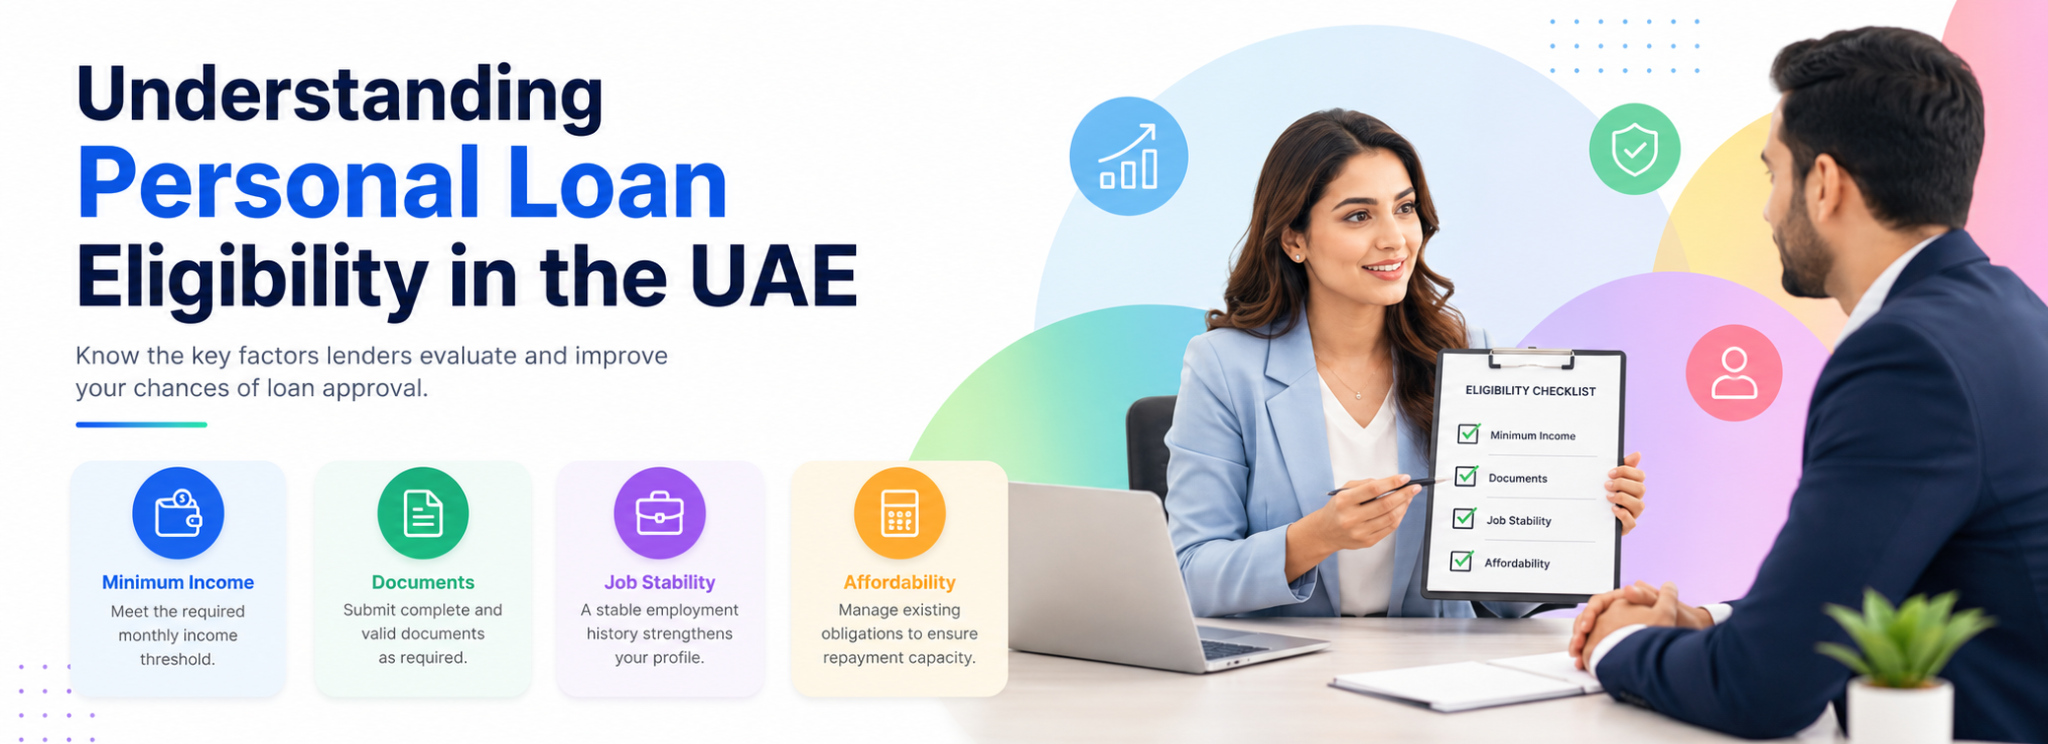
Personal loan eligibility in the UAE depends on more than salary. Lenders may also consider employment, existing debt, credit history and repayment capacity.
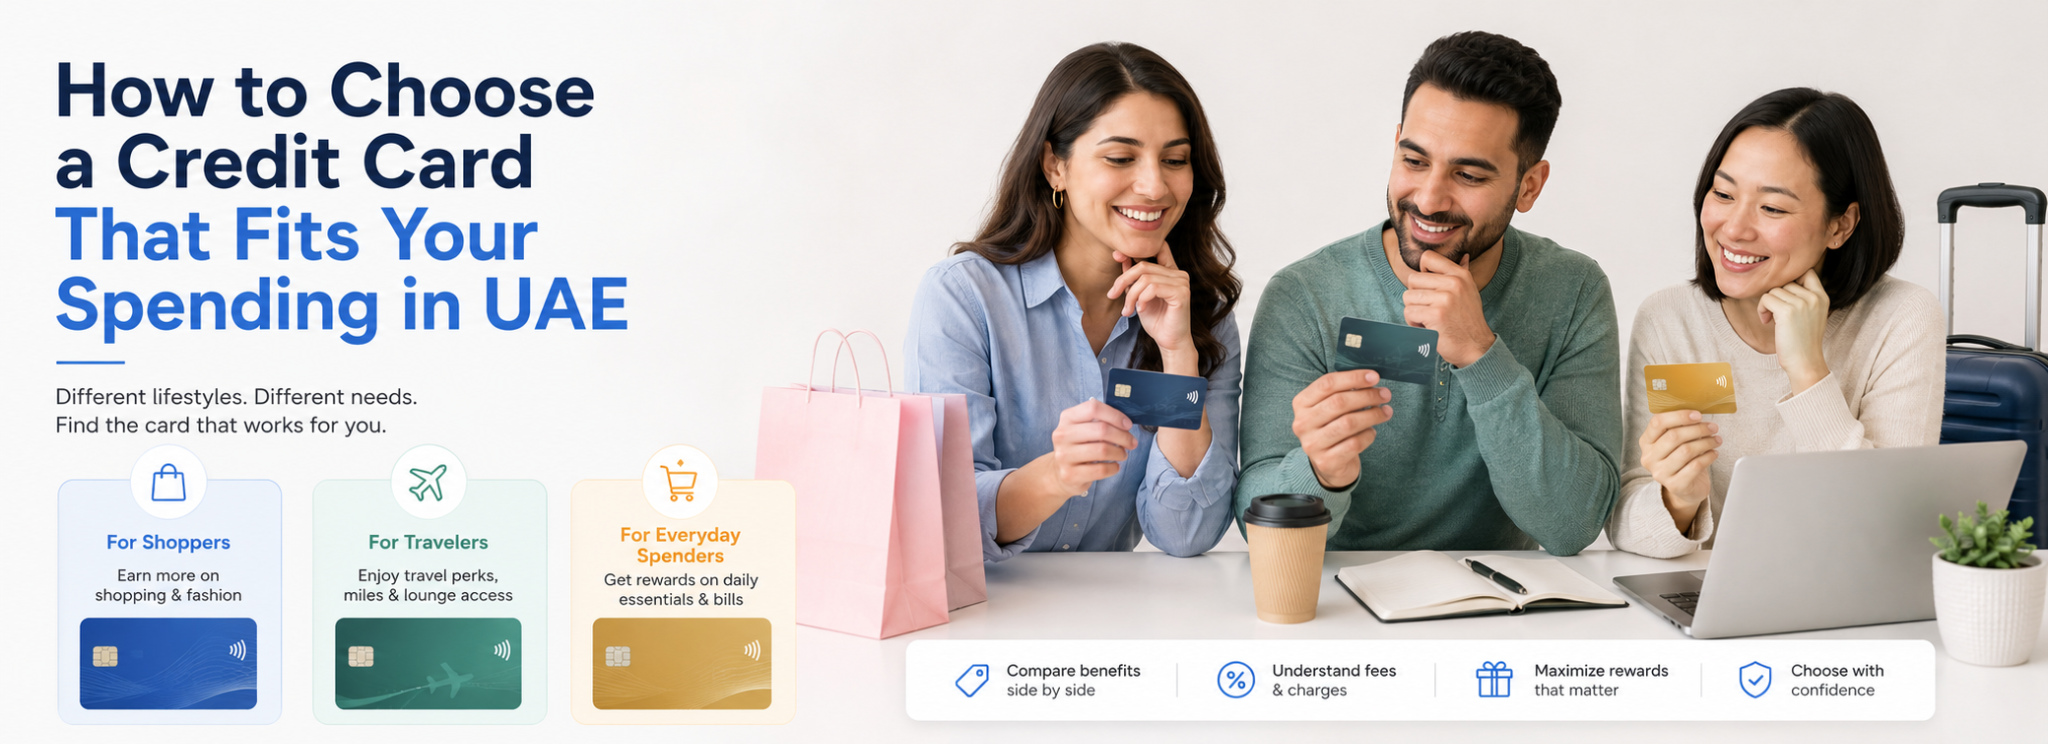
The right credit card should match how you already spend. Compare cashback, rewards, travel benefits, fees and limits before choosing a card in the UAE.
Planning the Abu Dhabi Grand Prix? Manage tickets, hotels, transport and dining while making better use of payments, travel rewards and card benefits.
Travelling for the FIFA World Cup? Check if your credit card covers lounges, travel insurance, foreign fees, rewards, backup payments and emergency support.
At this salary range, more card categories may become relevant. The smart move is to compare by real spending, repayment comfort and benefit usage.
AED 5,000 salary can be a starting point for selected entry - level credit cards in the UAE, but approval depends on the full profile.
Moving to the UAE comes with new banking decisions. This guide helps expats understand accounts, cards, loans and documents with more confidence.
Credit cards can be useful when used with discipline. These practical habits can help UAE residents get more value while avoiding common mistakes.
The best credit card is not the same for everyone. This guide explains how UAE residents can compare card categories based on salary, lifestyle, spending habits and repayment behaviour.
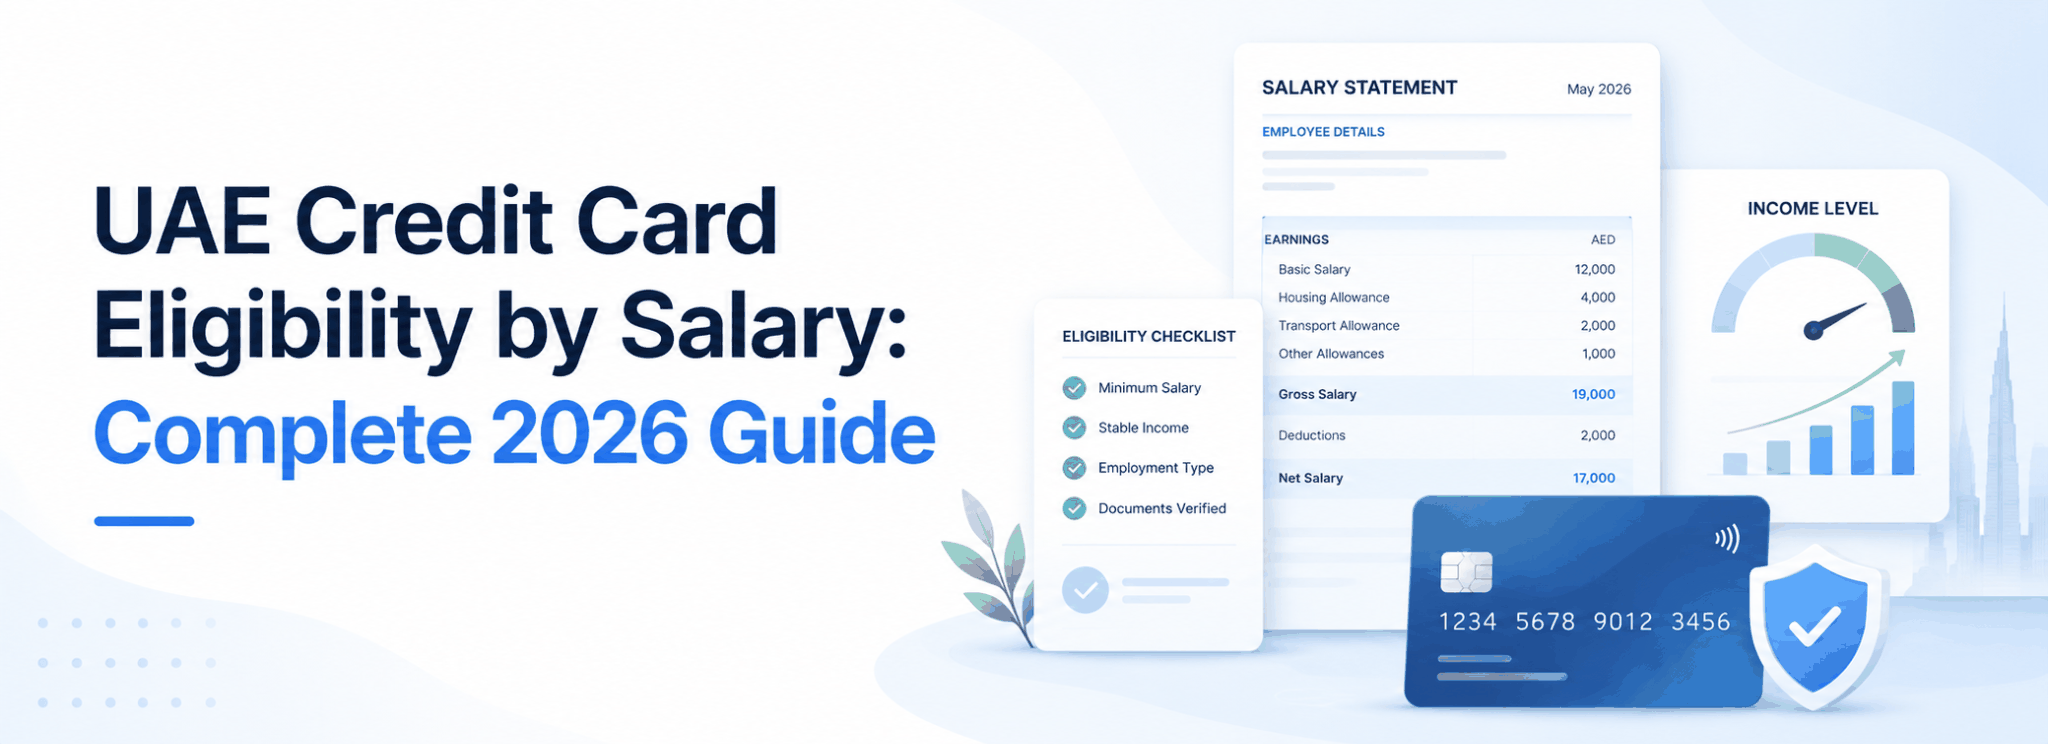
Your salary matters when applying for a credit card in the UAE, but it is only one part of the decision. This guide explains how UAE residents can think about eligibility with more clarity before choosing a card.
Your UAE credit score is the silent number shaping every card, loan, and approval you apply for. Build it with small, smart habits, and it turns money into freedom instead of friction.
Getting a personal loan in the UAE is easier when you know the rules. This guide helps you borrow smart with confidence and clarity.
Cashback offers simple, instant savings. Rewards points offer higher value with smart use.
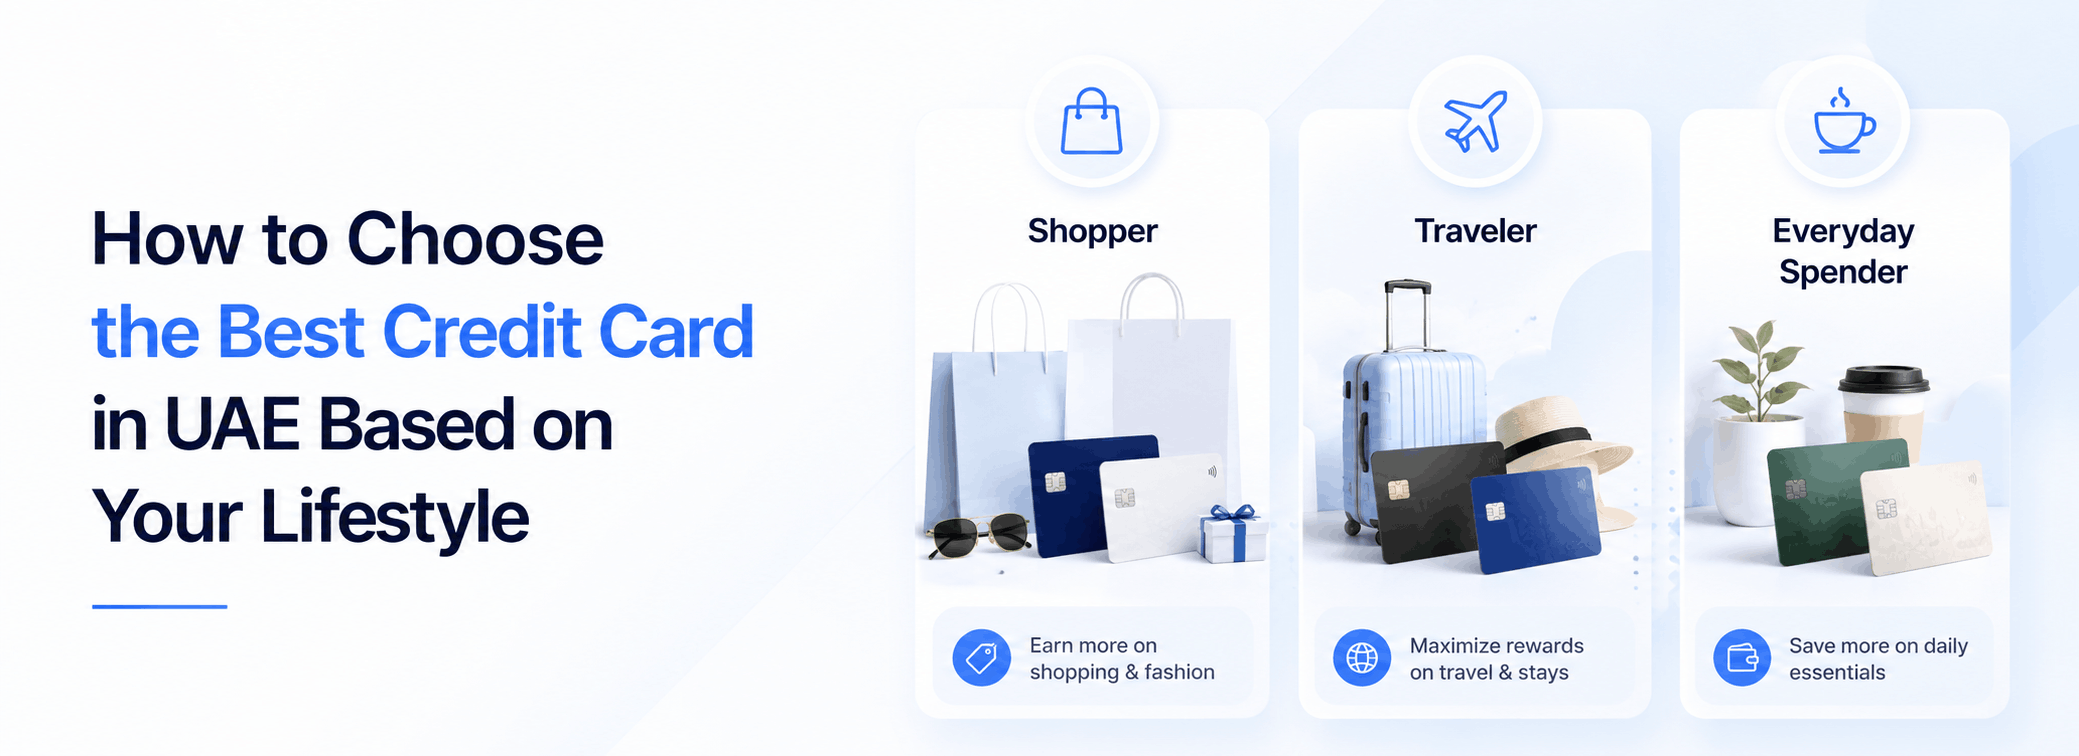
Choosing the right credit card isn’t just convenient - it’s a lifestyle upgrade. The right match can turn everyday spending into powerful rewards and savings.
 About the library
The FinShark articles library helps UAE residents understand everyday financial decisions — from choosing a credit card to understanding loan repayments, banking options and savings. Every guide is written in plain English, with AED-based examples and the local market in mind.
FinShark is a marketing and information platform, not a bank, lender or financial adviser. Our articles are designed to inform, not to push any single product. Where a topic connects to a tool — like Find My Card or our calculators — users can continue exploring options, subject to issuer or provider eligibility criteria.
UAE financial guidesFinancial products in the UAE can differ by issuer, provider, salary requirement, employment type, documents, fees, rewards structure, profit rate, interest rate and eligibility criteria. FinShark guides are built to help users understand these topics before they apply or speak with an authorised partner.
Understand card types, annual fees, rewards, cashback, minimum payments, interest/profit charges and eligibility criteria.
Learn how EMI, tenure, rates, DBR and documents may affect personal loan decisions in the UAE.
Read simple explainers on salary transfer, savings habits, banking terms and AED-based planning.
Explore by topicClear explainers on cashback, rewards, travel benefits, annual fees, minimum payments, interest/profit charges and card selection.
Understand EMI, repayment tenure, interest/profit rates, DBR, processing fees and documents commonly reviewed by providers.
Simple guides on salary transfer, bank accounts, banking relationships and common UAE banking terms.
Learn how rewards, cashback and air miles may work, including earn rates, redemption value, annual fees and practical usage.
Understand debt burden ratio, income, liabilities and why eligibility checks may vary by issuer or provider.
Practical guides on savings habits, budgeting, fixed deposits and AED-based financial planning.
Common questionsSalary requirements vary by issuer and card type. Some credit cards may have minimum salary criteria, while other checks may include employment type, documents, liabilities and credit profile.
DBR stands for debt burden ratio. It compares monthly debt payments with monthly income. Issuers and providers may use DBR as one part of their assessment, but it does not confirm approval or eligibility on its own.
A minimum payment is the amount a cardholder may need to pay by the due date. Paying only the minimum can increase the time taken to clear the balance and may increase interest/profit charges.
A personal loan is usually repaid through fixed monthly installments over a selected tenure, while a credit card is a revolving credit facility. The right option depends on usage, repayment ability, fees, rates and issuer/provider terms.
Cashback, rewards and miles may provide value based on spending, earn rates, redemption rules and annual fees. Actual value depends on how the card is used and the issuer's rewards programme terms.
Commonly requested documents may include Emirates ID, passport and visa details, salary certificate or payslips, bank statements and other documents requested by the issuer or provider. Requirements can vary.
Keep exploringAfter reading a FinShark guide, users can continue with practical tools to estimate payments, understand credit card costs or explore options based on their profile. These tools provide indicative information only and do not confirm approval or eligibility.
FAQsNo. FinShark articles are for general information and education only. They do not constitute financial advice, final decisions, product recommendations or issuer/provider criteria.
Yes. FinShark articles are written with UAE residents in mind and focus on topics such as credit cards, loans, banking, salary transfer, DBR, rewards and AED-based financial decisions.
FinShark may add new articles as the platform grows and as users need more clarity around financial products, tools and common questions in the UAE.
Users can explore relevant tools such as Find My Card or calculators after reading an article. Any application, eligibility, approval, pricing or terms depend on the relevant issuer or provider criteria.
FinShark articles are prepared for general information using a clear editorial approach. Content is designed to explain financial topics simply and should not be treated as financial advice.
No. FinShark articles are designed to explain topics and guide users through key considerations. Product availability, issuer participation, eligibility criteria and terms may vary.