Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
The Right Home Starts
With Financing That Fits.
Finding the property is one decision.
Financing it is another.
Explore home loan options based on your profile, income, property plans and financing needs — with more clarity before you proceed.
Let's Find Your Home Loan Options
Tell us a little about yourself and your property plans so we can show available home loan options from selected providers.
You may already know what you're looking for. Your first home. More space. An investment. A new beginning.
The next question is — what financing works for you?
A Home Is a Big Decision.
So Is How You Finance It.
The monthly payment is only part of the picture.
Your financing amount, repayment period and upfront contribution can all affect the commitment you take on. What matters is understanding the structure before you proceed.
- How much of the property you need to finance.
- How the repayment fits your monthly finances.
- How the financing period can affect your long-term commitment.
The property should fit your plans. The financing should fit them too.
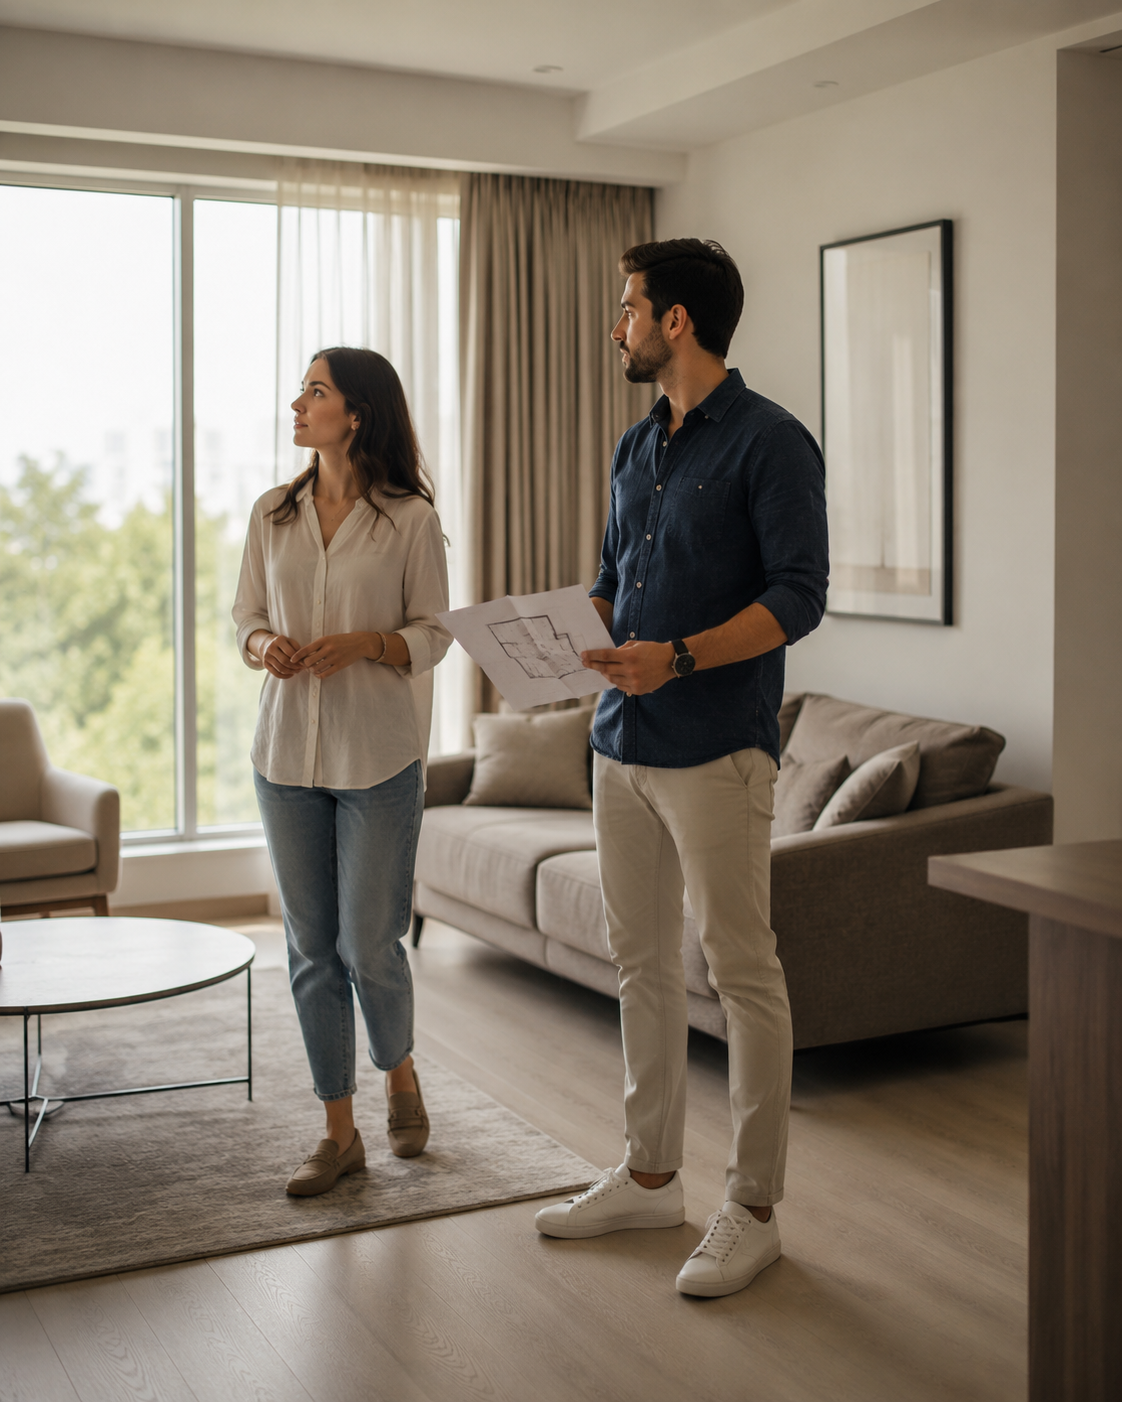
Think BeyondThe Purchase Price.
Your financing decision should be considered the same way.
Example scenario for illustration only and not an actual quote, valuation or offer.
Home Loans in the UAE:
What to Know Before You Apply
A home loan can involve more than choosing a property and a monthly repayment. Your income, existing commitments, property details, financing requirement and the provider's criteria can all influence the options available to you.
Affordability & Income
Your income, employment profile and existing financial commitments may be considered when a provider assesses affordability.
Property Value & Eligibility
The property's value, type and other applicable criteria can influence the financing available.
Your Contribution
Consider how much you plan to contribute yourself and the financing amount you may require.
Tenure, Rates & Fees
Review the repayment period, applicable rate structure, fees and other costs when assessing a home loan.
Frequently asked questions
How do home loans work in the UAE?
A home loan allows eligible buyers to finance part of a property's purchase price and repay the financing over an agreed period. Eligibility, rates, property requirements and financing amounts depend on the provider.
How much can I borrow for a home in the UAE?
The amount depends on your income, financial commitments, property value and the provider's affordability and eligibility assessment.
Do I need to have a property selected before applying?
Not necessarily. Some users begin exploring financing while still searching for a property, while others apply after identifying a specific home.
What costs should I consider besides the mortgage payment?
Potential costs can include your own contribution, valuation costs, registration-related expenses, provider fees and other property purchase charges.
Does FinShark provide mortgages directly?
No. FinShark helps users find and apply for home financing options from relevant providers. The financing itself is provided by the respective lender.
Ready to Find Home Financing That Fits?
Explore home loan options around your profile, property plans and financing needs.
Find. Select. Apply.
Find My Home LoanExplore Other Products
Discover more ways to find financial products that fit your needs.