
 Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
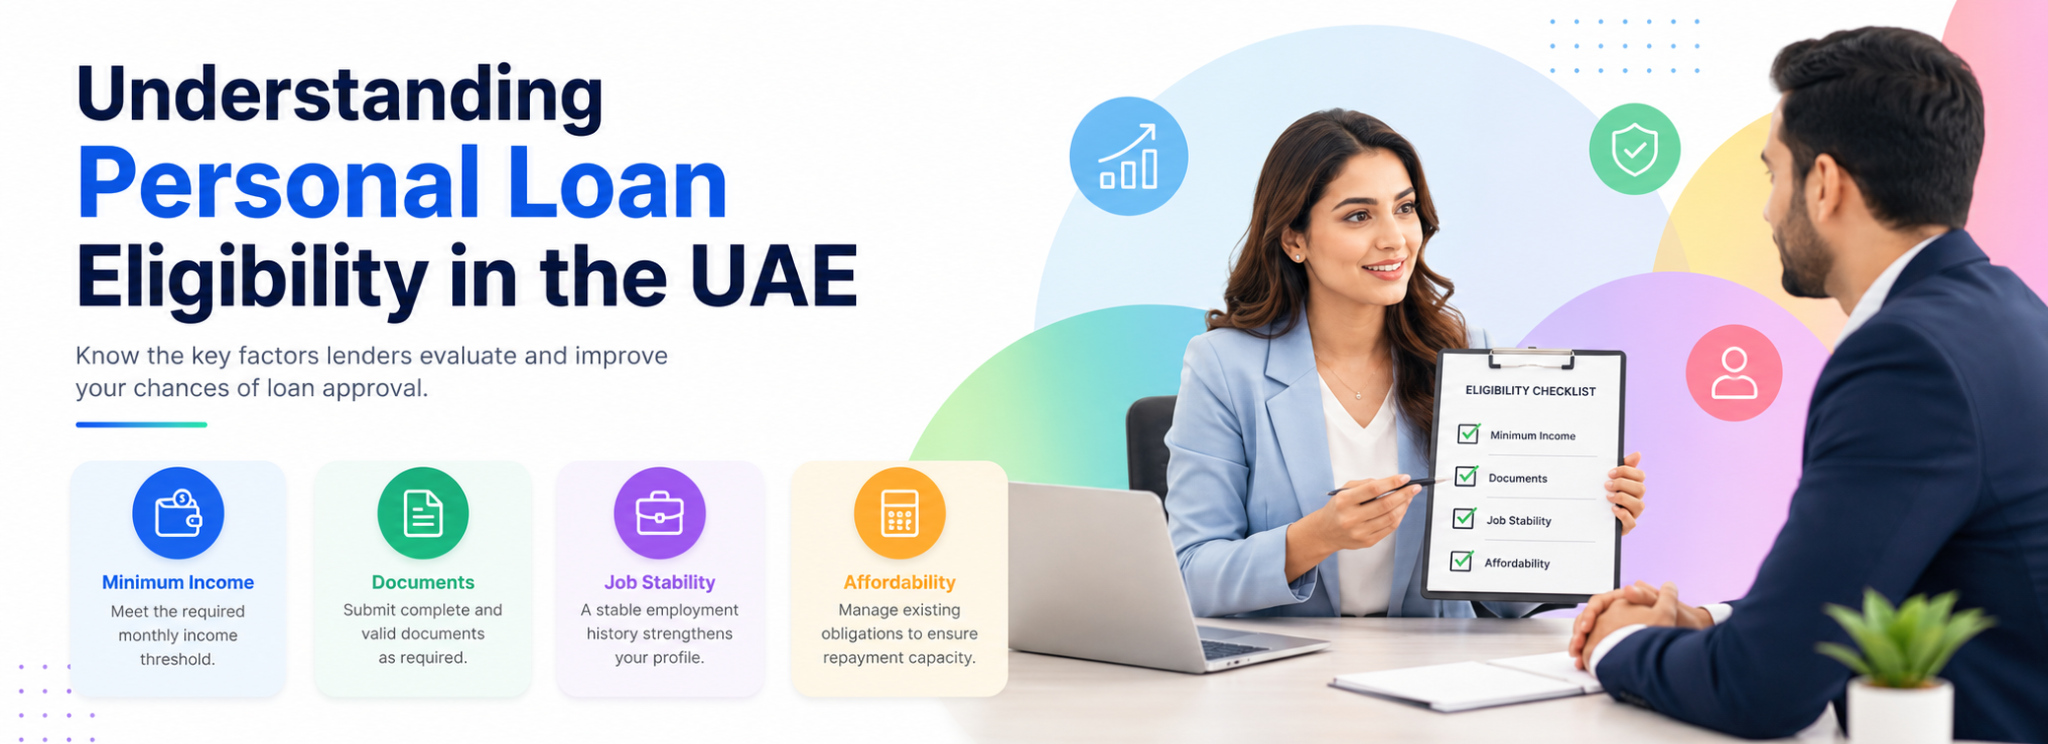
- Salary is an important starting point, but it does not determine personal loan eligibility on its own.
- Existing loans, credit card commitments and DBR can affect how much additional borrowing may be manageable.
- Credit history and repayment behaviour may form part of the lender’s assessment.
- Employment stability and complete documentation can influence how an application is evaluated.
- The amount you can potentially borrow is not necessarily the amount you should borrow.
Understanding Personal Loan Eligibility in the UAE
Thinking about a personal loan in the UAE usually starts with one question:
Am I eligible?
Salary is important, but personal loan eligibility is rarely determined by income alone.
Lenders may consider your employment, existing financial commitments, credit history, repayment capacity and supporting documents before deciding whether a loan fits your profile.
That is why two applicants earning similar salaries can receive different outcomes.
Understanding these factors before applying can help you make a more realistic borrowing decision.
Salary is only the starting point
Income helps a lender understand whether you may be able to support a new monthly repayment.
But the amount you earn does not show how much of that income is already committed elsewhere.
Someone with a higher salary but several existing loans and credit card obligations may have less room for another repayment than someone earning less but carrying very little debt.
The lender may therefore assess your salary alongside your wider financial position.
Employment stability can also matter. Length of service, salary consistency, probation status and employer-related criteria may form part of the assessment depending on the lender and product.
A higher income can widen the range of products that may be relevant to you, but it does not guarantee approval.
Existing debt and DBR matter
One of the key affordability considerations is how much of your monthly income is already being used to repay debt.
This can include personal loans, auto finance, credit card commitments and other borrowing.
Your Debt Burden Ratio (DBR) helps put those commitments into context by comparing debt repayments with regular income.
For borrowers, DBR is useful beyond eligibility.
It is also a practical way to ask whether another loan would leave enough room for normal life — rent, groceries, transport, family expenses, savings and unexpected costs.
Even if you qualify for additional borrowing, that does not mean taking the maximum possible amount is a good idea.
The right loan amount should fit comfortably within your budget.
Credit history can influence the application
Your previous borrowing behaviour may also form part of the lender’s decision.
A credit profile can give lenders an indication of how existing and previous financial commitments have been managed.
Repayment history, outstanding balances, existing facilities and recent borrowing activity may all contribute to the overall assessment.
In the UAE, lenders may use information available through Al Etihad Credit Bureau as part of their credit decision process.
But credit history should not be viewed as a simple pass-or-fail score.
Lenders may combine bureau information with their own eligibility criteria, affordability checks and internal policies.
A strong credit profile can support an application, but it does not guarantee that every lender or product will be suitable.
Employment and documentation help complete the picture
A lender generally needs to verify that your income is regular and sustainable.
For salaried applicants, employment information may therefore be reviewed together with salary.
Depending on the lender, this can include your employer, length of service, employment status and how salary is received.
Documentation is equally important.
Applicants may be asked to provide identification, residency information, salary evidence, bank statements or employment-related documents depending on their profile and the product.
Missing or inconsistent documents can slow down an application even when the financial profile appears suitable.
Preparing the required information in advance can make the process more straightforward.
Self-employed applicants may be assessed differently
For a self-employed resident, income may not arrive as a fixed salary every month.
The lender may therefore need a broader view of the applicant’s financial position.
This can include business and personal bank statements, trade licence information, business history and evidence of sustainable income.
It is important to distinguish business turnover from personal repayment capacity.
A business may generate substantial revenue while also carrying significant expenses.
The lender ultimately needs to understand whether the borrower has reliable capacity to meet the loan repayment.
This can make self-employed applications more detailed than straightforward salaried applications.
Loan amount and tenure also affect affordability
Eligibility is not simply about whether a lender says yes or no.
The amount borrowed and the repayment period can change the monthly commitment significantly.
A longer tenure can reduce the monthly instalment, but it may increase the total cost of borrowing. A shorter tenure may reduce the overall cost but create a larger monthly payment.
That is why comparing only the monthly EMI can be misleading.
The better approach is to look at the loan amount, tenure, monthly payment and overall borrowing cost together.
A smaller monthly instalment is not automatically the cheaper option.
Approval is not the same as affordability
This is one of the most important things to understand about personal loans.
A lender may approve an amount that is technically within its eligibility criteria.
That does not automatically mean borrowing the full amount is right for you.
Think about what happens after the loan is approved.
Can you still save each month? Would the repayment remain comfortable if your expenses increased? Could you continue managing it if your employment situation changed?
The approved amount should be treated as a maximum available limit, not a target.
Borrow based on what you actually need.
Why personal loan applications may be declined
There is no single reason a personal loan application may not proceed.
Income, existing obligations, credit history, employment details, documentation, requested loan amount and internal lender criteria can all play a role.
A decline also does not automatically mean the applicant has a poor financial profile.
The particular loan or lender may simply not be the right match.
Instead of immediately applying everywhere else, it is better to understand your financial position and identify what may have affected the application.
That can help make the next decision more informed.
Check your profile before applying
Before submitting an application, take a simple look at your own finances.
Understand your regular monthly income, how much you already repay toward debt and what room remains in your budget.
Then consider whether your employment and income are stable, whether your documents are ready and how much you genuinely need to borrow.
Most importantly, calculate the monthly repayment before committing.
A Personal Loan EMI Calculator can help you understand how changing the loan amount or tenure may affect the monthly instalment.
The goal is not simply to qualify.
It is to choose a repayment that remains manageable.
How FinShark helps
FinShark helps UAE residents explore personal loan options based on their profile, borrowing requirements and repayment preferences.
You can also use FinShark calculators to understand how different loan amounts and repayment periods may affect your monthly commitment before exploring available options.
FinShark does not lend money or make approval decisions. Personal loans are provided by third-party lenders and remain subject to lender eligibility criteria, affordability assessment, documentation, pricing and terms.
Closing
Personal loan eligibility in the UAE is based on the overall financial picture.
Salary matters, but so do existing commitments, DBR, credit history, employment stability and documentation.
Before applying, understand what you need to borrow and what you can comfortably repay.
Getting approved is only part of the decision.
Making sure the loan fits your finances is the more important part.
Ready to put this into action?
Explore credit card options that may suit your profile, or estimate the numbers first with our UAE calculators. Eligibility applies.
This article is for general information only and does not constitute financial advice. FinShark is a marketing and information platform, not a bank, lender or financial adviser. Products are offered by third-party issuers and are subject to issuer eligibility criteria, fees, documentation and terms. T&Cs apply.