
 Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
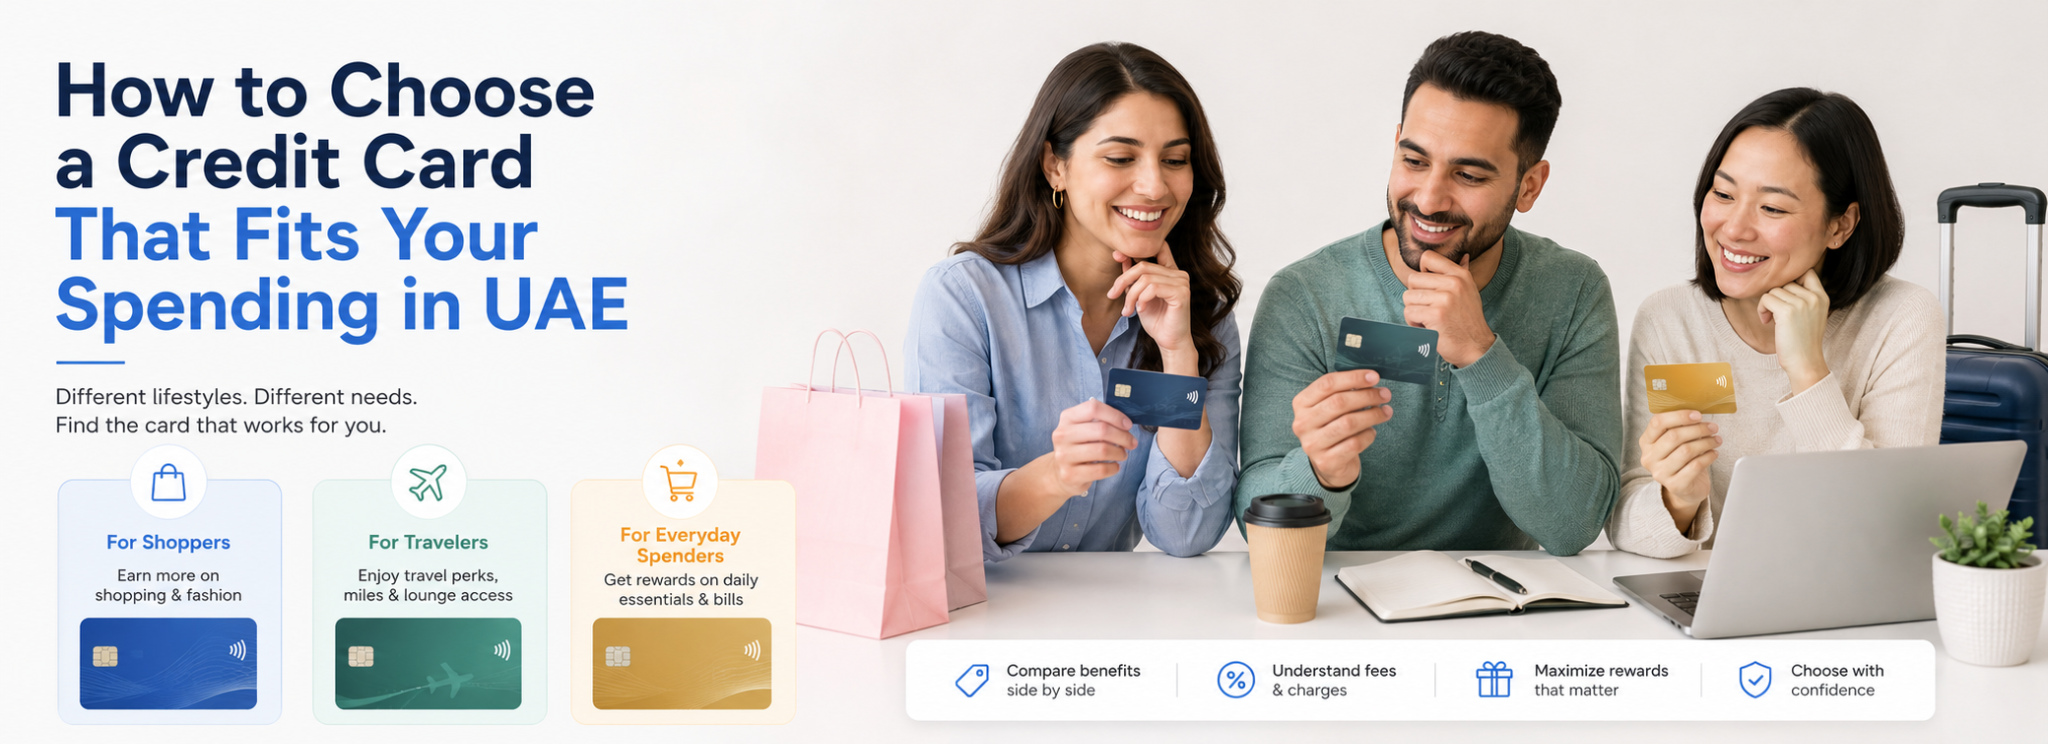
- Start by reviewing where your money actually goes each month before comparing credit cards.
- Cashback, rewards and travel cards can offer very different value depending on your spending habits.
- Annual fees, reward caps, exclusions and minimum-spend conditions can reduce the real value of card benefits.
- A premium card is not automatically better if you rarely use the benefits it provides.
- Choose a card that fits both your spending pattern and your ability to repay the balance comfortably.
How to Choose a Credit Card That Fits Your Spending in UAE
Choosing a credit card in the UAE can become confusing quickly. One card promises cashback, another focuses on travel miles, while others highlight dining, fuel, online shopping or airport benefits.
The easiest way to narrow the choice is not to start with the card.
Start with how you already spend.
A useful credit card should fit your existing lifestyle and reward expenses you were going to make anyway. It should not push you to spend more simply to unlock cashback, points or benefits.
Start with how you actually spend
Look at your last two or three months of transactions and identify where most of your money goes.
For one household, groceries and fuel may dominate the monthly budget. Someone else may spend more on dining and online shopping. A frequent traveller may put a significant amount toward flights, hotels and overseas transactions.
Those people should not necessarily choose the same card.
If groceries, fuel and everyday purchases make up most of your spending, a cashback-focused card may be a sensible place to start. If you travel regularly, miles, lounge access and travel-related benefits may matter more. Someone who spends heavily on dining or online shopping may want a card that rewards those categories instead.
You do not need to optimise every transaction. Focus on the two or three categories where you consistently spend the most.
That immediately makes comparing cards easier.
Cashback, miles or rewards: what fits you?
Cashback is usually the simplest reward to understand.
You spend on an eligible transaction and receive part of that amount back according to the card's terms. This can work well for UAE residents whose spending is concentrated around everyday expenses such as groceries, fuel, dining or general retail.
But do not choose a card based only on the headline cashback rate.
A high percentage may come with a monthly cap, minimum-spend requirement or category restrictions. What matters is the cashback your normal spending would realistically earn after those conditions.
Miles and travel rewards work differently.
They may suit residents who fly regularly, stay in hotels, spend internationally or understand how to use airline reward programmes effectively. Benefits such as airport lounge access or travel-related privileges can add value as well.
However, a travel card is only useful when you actually use those benefits. Someone flying once every year or two may get more practical value from straightforward cashback than from paying for premium travel features.
The better question is not whether miles or cashback are generally better.
It is which reward are you more likely to use?
Check the real value, not the headline benefit
Credit cards often look most attractive at the top of the product page.
The real value usually becomes clearer when you look at the conditions.
An annual fee may be worth paying if you regularly use the card's benefits. A frequent traveller might get enough value from lounge access, insurance or travel rewards to justify it. Someone whose spending is mostly local may find a simpler card more useful.
Reward caps matter too.
A card can advertise strong cashback but limit how much you can earn every month. Minimum-spend conditions can also change the equation, particularly if you need to spend more than you normally would just to unlock a benefit.
That is usually a sign the card may not fit your spending.
The same principle applies to premium cards. More benefits do not automatically mean more value.
If you rarely use the benefits, you are simply paying for features that look good but do little for your everyday finances.
If you travel or spend internationally
UAE residents who travel frequently or shop from international websites should pay closer attention to overseas spending.
A card may offer extra miles or rewards on foreign transactions, but currency-related charges can reduce the benefit.
For example, earning additional rewards on an overseas purchase may look attractive until foreign transaction costs are taken into account.
This is why travel cards should be compared on the complete experience rather than the reward rate alone.
Look at how the card handles international spending, whether overseas purchases earn rewards and whether the travel benefits are genuinely useful for the way you travel.
Airport lounge access is a good example.
It can be valuable for someone flying several times a year. But if you rarely travel, lounge access may not justify choosing a more expensive card.
The same applies to hotel privileges, travel insurance and miles.
Benefits are valuable only when you use them.
Repayment and eligibility matter more than rewards
A credit card can offer excellent cashback or miles and still be the wrong card for your financial situation.
Rewards only make sense when your spending remains manageable.
If balances are regularly carried and finance charges apply, those costs can quickly outweigh the value of cashback or points.
So before comparing rewards, think about what you normally spend each month and whether you can comfortably manage the repayment without putting pressure on rent, household expenses, savings or other obligations.
Eligibility matters too.
Even if a card fits your spending perfectly, the issuer may assess factors such as income, employment, existing obligations, credit history, documentation and internal eligibility criteria.
There are therefore two questions worth answering:
Does this card fit the way I spend?
Does this card fit my financial profile?
A strong choice needs to satisfy both.
A simple way to choose
You do not need to compare every credit card in the UAE.
Start by identifying your largest monthly spending categories. Decide whether cashback, miles or another reward structure would be most useful. Then compare the annual cost, important conditions and whether the benefits fit your real lifestyle.
Finally, check whether the card is appropriate for your income and eligibility profile.
The right credit card is not necessarily the one with the highest reward rate, the most premium branding or the longest list of benefits.
It is the card that fits comfortably into the way you already spend and repay.
A credit card should make your existing spending more useful.
It should not give you a reason to spend more.
Ready to put this into action?
Explore credit card options that may suit your profile, or estimate the numbers first with our UAE calculators. Eligibility applies.
This article is for general information only and does not constitute financial advice. FinShark is a marketing and information platform, not a bank, lender or financial adviser. Products are offered by third-party issuers and are subject to issuer eligibility criteria, fees, documentation and terms. T&Cs apply.