
 Home
 Credit Cards
 Personal Loans
 Car Loans
 Home Loans
 Business Loans
 Bank Accounts
 Calculators
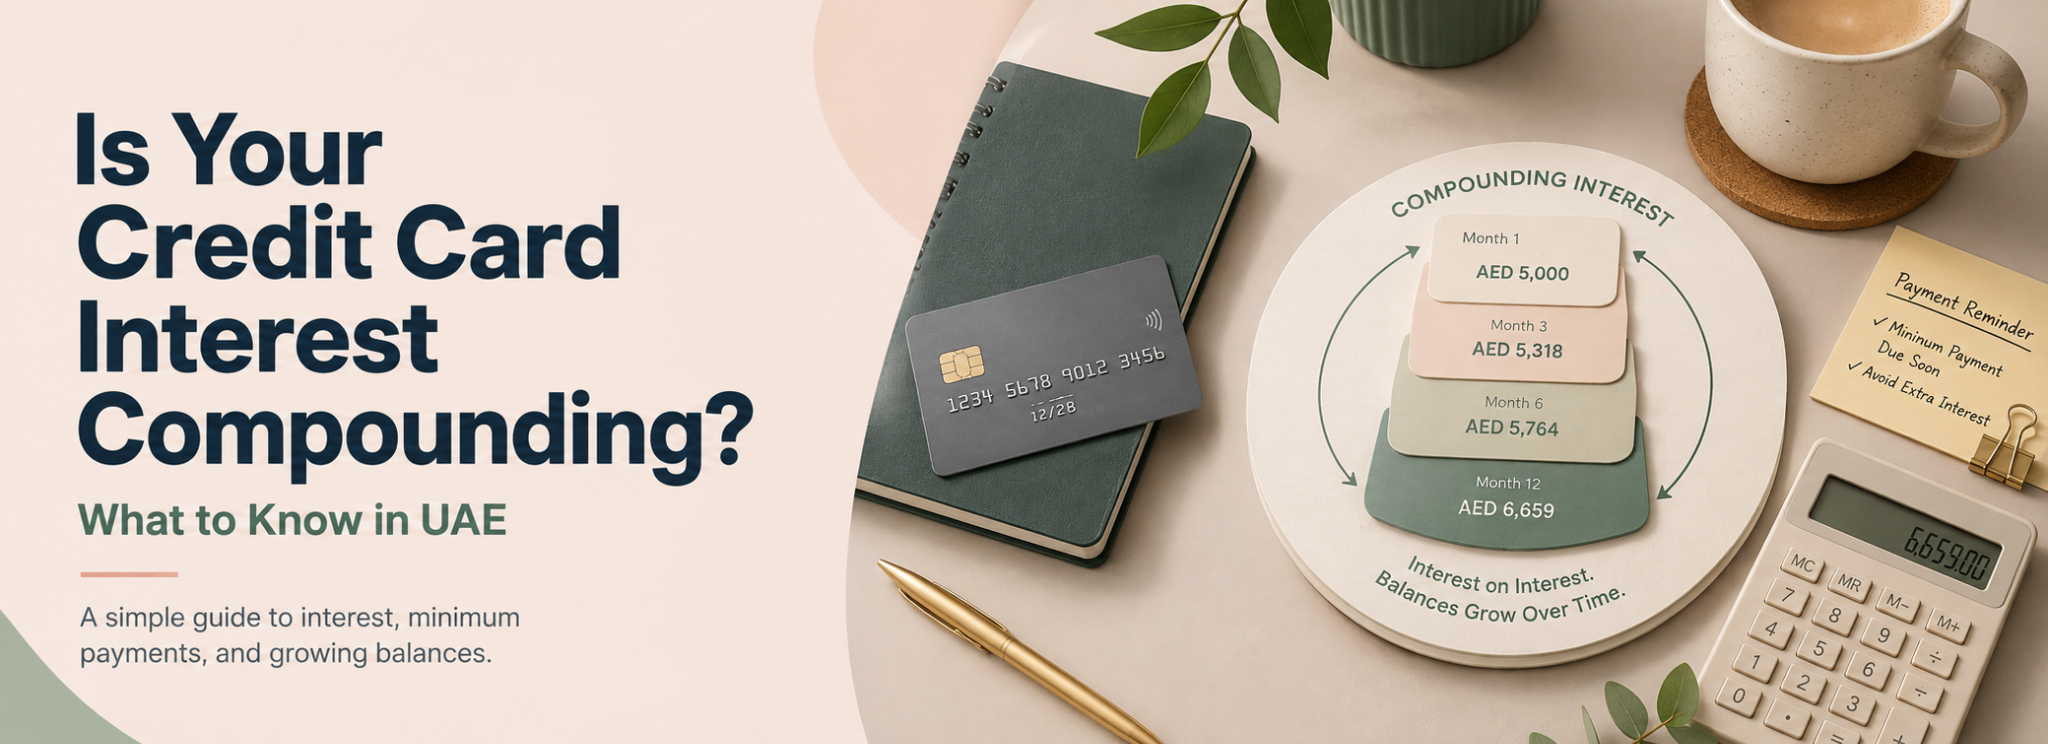
- Credit card finance charges can significantly increase the cost of purchases when balances are carried forward.
- The exact way charges are calculated depends on the card issuer and its current terms.
- Paying only the minimum can keep a balance outstanding for much longer.
- Continuing to spend while repaying old debt can make it harder to reduce the balance.
- Understanding the total repayment cost matters more than looking only at the minimum amount due.
Is Your Interest Compounding? The Truth About Credit Card Debt
A credit card purchase can feel very different depending on how you repay it.
Buy something for AED 1,000 and repay the full statement according to the card terms, and the cost may remain close to what you originally spent.
Carry that balance forward for several months, however, and finance charges can increase the amount you ultimately repay.
This is where people often describe credit card interest as “compounding”.
The idea is broadly useful: when debt remains unpaid, borrowing costs can continue to build around that outstanding balance. But the exact calculation method, timing and treatment of finance charges varies between issuers and products.
What matters most for cardholders is simpler:
The longer expensive card debt remains outstanding, the more it can cost.
Why a credit card balance can grow
When you do not repay the amount required to avoid finance charges under your card's terms, the unpaid balance may begin attracting charges.
The next statement can then include your remaining balance, applicable finance charges, new purchases and any other relevant fees.
If you continue using the card while paying down an older balance, new spending can make the total harder to reduce.
This is why someone can make a payment every month and still feel as though the balance is barely moving.
Part of the payment may be going toward the cost of carrying the debt rather than reducing the original spending as quickly as expected.
Is credit card interest actually compounded?
This needs some care.
Credit card issuers can calculate finance charges in different ways, and the precise methodology is defined by the card's terms and conditions.
Depending on the product, charges may be linked to an annual rate, monthly rate, daily balance or another calculation method.
So it is better not to assume every UAE credit card uses exactly the same form of compounding.
However, from the customer's perspective, the effect can feel similar: keeping an outstanding balance for longer can increase the total amount paid.
The safest approach is to check your own card's current schedule of fees, finance-charge methodology and statement information rather than relying on a generic percentage.
Why minimum payments can be misleading
The minimum payment shown on a credit card statement is the smallest amount required under the issuer's terms for that billing period.
It is not necessarily the amount that clears the debt efficiently.
Paying only the minimum can keep a balance outstanding for much longer, particularly if you continue making new purchases.
That does not mean the minimum payment is unimportant. Missing it can lead to additional consequences under the card terms.
But there is an important distinction between:
making the required payment
and
repaying the debt quickly.
If your objective is to reduce the balance, paying more than the minimum where financially possible can make a significant difference.
New spending can slow repayment
Imagine you are trying to clear an existing card balance but continue using the same card for groceries, dining and online shopping every month.
Even if you make regular repayments, the new purchases keep adding to the balance.
The result can become a moving target.
For someone trying to get out of card debt, temporarily reducing new discretionary spending on that card can make progress easier to see.
This does not mean every card must be stopped completely.
It means repayment works better when you understand whether the balance is actually falling from month to month.
The headline rate does not show the full cost
Credit card users sometimes focus on the advertised annual or monthly finance rate.
But the actual cost of carrying debt depends on more than one number.
The balance, repayment amount, repayment timing, new purchases and applicable fees can all influence how much you eventually pay.
A relatively small balance carried for a short time is very different from a large balance that stays outstanding for a year.
That is why the more useful question is not simply:
“What is my card's rate?”
It is:
“How much will this balance cost me if I repay it at my current pace?”
A Credit Card Interest Calculator or repayment calculator can help make that clearer.
A simple example
Suppose you have a credit card balance and decide to make only small payments each month.
The balance reduces, but slowly.
During that period, finance charges may continue to apply according to your issuer's terms. If you add new purchases as well, the total can remain high despite several months of payments.
Now compare that with making a larger repayment and avoiding new discretionary spending on the card.
More of the debt can disappear sooner, which may reduce the period over which finance charges apply.
The principle is straightforward:
Repayment speed matters.
Cash advances can be different
Cash withdrawals using a credit card deserve particular caution.
Cash advances can follow different fee and finance-charge rules from normal retail purchases.
They may also begin attracting charges differently depending on the issuer.
For that reason, withdrawing cash on a credit card should not automatically be treated like making a normal card purchase.
Check the specific cash-advance terms before using the facility.
What if you have balances on several cards?
Multiple card balances can make repayment harder because each card may have a different due date, minimum payment and finance-charge structure.
The first step is simply to understand what you owe.
List the outstanding balance on each card, the applicable cost of carrying it and the required payment.
From there, you can decide how to direct any extra repayment capacity.
Some people prefer clearing a smaller balance first for momentum. Others focus on the most expensive debt first.
The important part is having a deliberate plan rather than making random payments across several cards.
Balance transfer can help, but it is not a reset button
A balance-transfer facility may allow eligible customers to move outstanding card debt under different repayment terms.
This can potentially make repayment easier to organise.
But the benefit depends on the actual offer.
Processing fees, promotional periods, subsequent rates and repayment terms all matter.
And transferring a balance does not solve the problem if the original card is immediately used to build up new debt again.
A balance transfer should support a repayment plan, not create additional spending capacity.
Repayment should come before rewards
Cashback, miles and reward points are useful when the card is being managed well.
They become far less important when significant finance charges are being paid on an outstanding balance.
There is little value in earning a small amount of cashback if carrying the purchase costs considerably more.
If you are already carrying card debt, prioritising repayment may provide more financial benefit than optimising rewards.
Rewards work best when they sit on top of spending you can already afford.
What to do if the balance is becoming difficult to manage
If your balance is rising despite regular payments, do not ignore it.
Start by reviewing the statements and understanding the amount owed, finance charges and new spending.
Reduce avoidable card spending where possible and work out what monthly repayment is realistically sustainable.
If repayment is becoming genuinely difficult, contact the issuer early rather than waiting for missed payments to accumulate.
Depending on the circumstances, the issuer may be able to explain available repayment or restructuring options.
The key is to address the problem while there are still choices available.
The better way to think about card debt
Credit cards are designed to provide flexibility.
That flexibility becomes expensive when a balance turns into long-term borrowing without a clear repayment plan.
You do not need to understand every mathematical detail of interest calculation to make a better decision.
You need to know three things:
How much you owe.
How much it is costing to carry.
And how quickly your current repayment will reduce it.
Once those are clear, the debt becomes much easier to manage deliberately.
How FinShark helps
FinShark provides calculators and guides that can help UAE residents understand the cost of credit card borrowing.
A Credit Card Interest Calculator can help illustrate how carrying a balance may affect repayment, while a Minimum Payment Calculator can show why small monthly payments can keep debt outstanding for longer.
FinShark does not issue credit cards or provide debt advice. Card terms, finance charges, fees and repayment requirements remain subject to the relevant issuer.
Closing
The real problem with credit card debt is not simply whether the interest is technically “compounding”.
It is what happens when an expensive balance stays unpaid for too long.
Finance charges can increase the total cost, minimum payments can stretch repayment and new spending can slow progress further.
Understand your balance, check your issuer's terms and focus on reducing the debt rather than only meeting the minimum.
The faster expensive debt disappears, the less opportunity it has to keep costing you.
Ready to put this into action?
Explore credit card options that may suit your profile, or estimate the numbers first with our UAE calculators. Eligibility applies.
This article is for general information only and does not constitute financial advice. FinShark is a marketing and information platform, not a bank, lender or financial adviser. Products are offered by third-party issuers and are subject to issuer eligibility criteria, fees, documentation and terms. T&Cs apply.